What Poor Data Governance Is Actually Costing You: The Financial Reckoning Most Enterprises Avoid
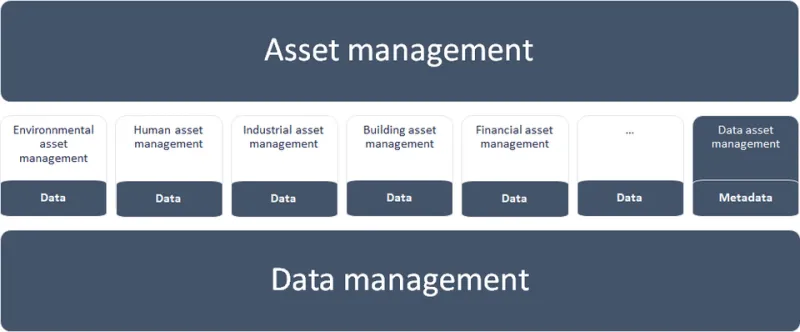
Photo: Bmagoni, CC BY-SA 4.0, via Wikimedia Commons
There is a particular kind of organizational expense that never appears as a line item in quarterly reviews. It does not trigger an alert in your ERP system. No department head raises it during budget season. Yet it accumulates with the quiet persistence of interest on unpaid debt—eroding margins, inflating headcount requirements, and multiplying the cost of every strategic initiative your organization attempts to execute.
That expense is the operational burden of poor data governance. And for most US enterprises, it is substantially larger than leadership believes.
The Misclassification Problem
Before organizations can address governance-related costs, they must first recognize them for what they are. The challenge is that these costs rarely present themselves as data problems. They surface as project overruns. As IT remediation tickets. As compliance penalties attributed to process failures. As duplicated vendor contracts that no single system of record could have flagged. As analyst hours consumed not by generating insight, but by reconciling conflicting data sets before any analysis can begin.
This misclassification is not incidental—it is structural. When data quality failures create downstream operational friction, the friction gets assigned to the operational budget, not to a governance failure. The consequence is that the true cost of inadequate data stewardship remains invisible at the executive level precisely because it has been distributed across every other cost center in the organization.
A conservative estimate from industry research consistently places the cost of poor data quality at between 15 and 25 percent of total revenue for affected organizations. For a mid-size enterprise generating $500 million annually, that range represents $75 million to $125 million in preventable financial drag. The figure is striking. What is more striking is how rarely it is calculated with any rigor.
Where the Costs Actually Accumulate
A credible accounting of governance-related costs requires examining four distinct cost categories that most organizations treat as unrelated.
Redundant labor and duplicated effort. When data definitions are inconsistent across business units, analysts in different departments independently clean, transform, and reconcile the same underlying data. This is not inefficiency born of poor talent or weak management—it is a structural outcome of ungoverned data environments. The labor cost is real, recurring, and almost entirely preventable.
Compliance exposure and regulatory remediation. US enterprises operating under frameworks such as HIPAA, SOX, CCPA, or sector-specific federal regulations carry meaningful financial exposure when data lineage cannot be demonstrated, consent records are incomplete, or audit trails are fragmented. Regulatory penalties are the visible portion of this cost. The invisible portion—legal review, remediation engineering, compliance consulting, and executive time—typically exceeds the fine itself by a significant multiple.
Failed or delayed system integrations. Enterprise technology initiatives—ERP migrations, CRM implementations, data warehouse consolidations—routinely exceed budget and timeline projections. Post-project analysis consistently identifies data quality and schema inconsistency as primary contributing factors. When integration projects fail or require extended remediation, the root cause is frequently traced to governance deficits that were present long before the project began.
Strategic decision latency. This is the most underappreciated cost category. When leadership cannot trust the data, decisions are delayed, deferred to committee, or made with unnecessary conservatism. The opportunity cost of strategic hesitation driven by data uncertainty is rarely calculated—but in competitive markets, it is often the most consequential figure on the ledger.
A Framework for Calculating Governance ROI
Quantifying the return on data governance investment requires organizations to construct what might be called a governance cost baseline—a structured audit of current expenditures attributable to data quality failures and stewardship gaps.
The baseline assessment should proceed in three phases.
First, conduct a labor audit across all functions that regularly interact with enterprise data. Identify the proportion of analyst, IT, and operational time spent on data reconciliation, error correction, and manual workarounds rather than value-generating activity. Even a conservative estimate of this proportion, applied to fully loaded compensation costs, typically produces a significant annual figure.
Second, inventory compliance incidents and integration failures from the prior three fiscal years. For each incident, calculate total remediation cost—including internal labor, external consulting, system downtime, and any regulatory penalties. Categorize each incident by its data governance root cause. This exercise frequently reveals that a small number of recurring governance failures are responsible for a disproportionate share of total remediation spend.
Third, estimate strategic decision latency costs by identifying decisions that were delayed, reversed, or hedged due to data confidence issues. Apply a conservative revenue impact multiplier based on the competitive window that elapsed during the delay. This is inherently imprecise, but even rough estimates are sufficient to establish the order of magnitude.
The sum of these three components constitutes a defensible governance cost baseline. A properly scoped data stewardship program—with clear ownership, enforced data standards, and integrated quality monitoring—typically reduces this baseline by 40 to 60 percent within 18 to 24 months.
The Compounding Dynamic Leadership Must Understand
Data governance costs do not remain static. They compound. Every year that an organization operates with fragmented data definitions, inconsistent master data, and ungoverned data pipelines, the remediation cost of eventually addressing those problems increases. Legacy systems accumulate dependencies. Downstream applications are built on unreliable foundations. Regulatory obligations expand. The technical debt of poor governance is not linear—it accelerates.
This compounding dynamic is the central argument for treating data governance as a strategic investment rather than an administrative function. The question is not whether your organization can afford to implement rigorous data stewardship. The question is whether it can afford to continue absorbing the cost of not doing so.
Moving From Recognition to Action
For enterprise leaders who have not yet conducted a structured governance cost assessment, the immediate priority is establishing visibility. The costs are present in your organization's financial data today—they are simply misclassified, distributed, and invisible in aggregate form.
Begin with the labor audit. It requires no new technology investment, no external consulting engagement, and no executive approval beyond the commitment of two or three weeks of analytical time. The findings will almost certainly be sufficient to justify the broader assessment and, ultimately, the governance investment itself.
Data stewardship is not an IT problem that technology alone can resolve. It is an organizational discipline that requires defined ownership, executive sponsorship, and accountability structures that span business units. The enterprises that recognize this earliest will carry the smallest governance tax—and will compound the advantage with every passing quarter.